What is the structural scope and industry significance of the Digital Twin Retail Refrigeration Market?
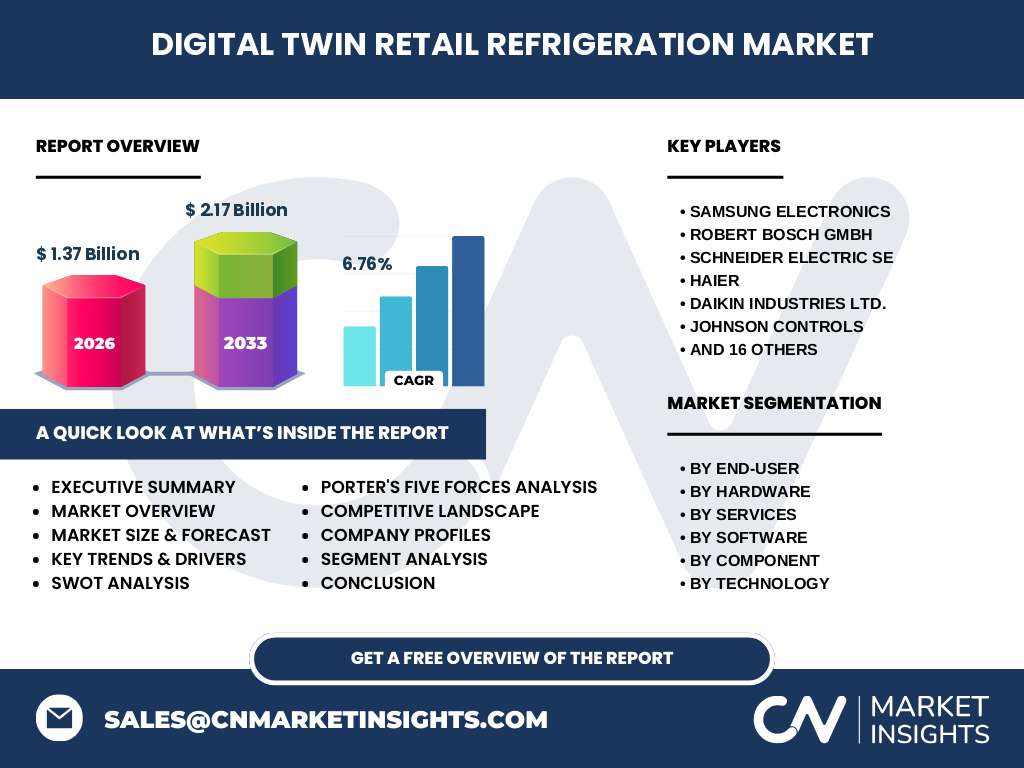
Our analysis indicates that the Digital Twin Retail Refrigeration Market represents a transformative paradigm in cold chain management, valued at $1.37 Billion in 2026. This sector bridges physical display cases and walk-in coolers with real-time virtual models, optimizing energy consumption under stringent ASHRAE and European F-Gas regulations across major supermarket logistics hubs.
Structural Growth Drivers and Restraints in the Digital Twin Retail Refrigeration Market
The market is propelled by strict environmental mandates targeting HFC refrigerants and escalating electricity costs in retail chains. However, high initial capital expenditures for deploying edge devices and IoT sensors across legacy distribution networks create friction, challenging smaller independent grocers attempting adoption.
Emerging Technological Trends Shaping the Digital Twin Retail Refrigeration Market
The convergence of Artificial Intelligence (AI) and Machine Learning with IoT telemetry is redefining predictive maintenance. Leading facilities now leverage advanced analytics and simulation tools to forecast compressor failures weeks in advance, drastically reducing food spoilage in pharmaceutical and high-density grocery supply chains.
COVID-19 Impact and Recovery Trajectory for the Digital Twin Retail Refrigeration Market
The pandemic accelerated contactless, automated supply chain visibility. As retail networks faced severe labor shortages and fluctuating cold-storage demands, investments in remote monitoring and control software surged, establishing a resilient baseline that now supports steady post-pandemic expansion.
Competitive Benchmarking and Strategic Dynamics
Market concentration is moderately high, dominated by industrial heavyweights like Danfoss A/S, Johnson Controls, and Schneider Electric SE. These innovators compete by integrating proprietary digital twin platforms with legacy hardware, providing end-to-end refrigeration optimization for global supermarket chains.
Executive Summary of the Digital Twin Retail Refrigeration Market
Our comprehensive research confirms a robust expansion trajectory, projecting the market to reach $2.17 Billion by 2033 at a CAGR of 6.76%. Adoption is heavily concentrated in energy-intensive commercial sectors seeking automated compliance and unprecedented thermal efficiency.
Market Forecast and Valuation Trajectory (2027 to 2033)
Driven by accelerating IoT sensor deployments and edge computing upgrades, the market will scale consistently from its 2026 baseline of $1.37 Billion to reach $2.17 Billion by 2033. This expansion reflects a steady 6.76% CAGR as sustainability mandates tighten globally.
Segmentation Analysis Across Hardware, Software, Services, and End-Users
The market bifurcates across critical pillars: hardware encompasses sensors, edge devices, and controllers; software integrates digital twin platforms and monitoring tools; services cover installation and consulting. End-users span food and beverage, retail chains, and pharmaceuticals, prioritizing display cases and walk-in freezers.
Geographic Distribution and Regional Market Performance
Regional performance varies based on local grid costs and green building codes. North America and Europe currently dominate adoption, driven by aggressive corporate net-zero targets among hypermarket chains, while Asia-Pacific emerges as the fastest-growing frontier due to rapidly expanding cold-chain infrastructure.
In-Depth Regional Review of Commercial Refrigeration Hubs
European markets lead in regulatory-driven adoption, complying strictly with EU F-Gas regulations through advanced IoT architectures. Meanwhile, North American retail giants leverage edge computing and AI simulation tools near major logistics distribution centers to slash multi-site energy expenditures.
Strategic Positioning of Leading Industry Innovators
Pioneering firms like Siemens Digital Industries Software, Axion Cloud Inc., and Gamma Technologies deliver specialized simulation software. Concurrently, equipment providers such as Hussmann Corp. and GEA Heating & Refrigeration Technologies embed intelligent controllers directly into industrial freezers.
Porter's Five Forces Analysis of the Industry Landscape
Rivalry is intense among established automation conglomerates, while the threat of new entrants remains moderate due to high software integration barriers. Supplier power is tempered by numerous component manufacturers, but buyer bargaining power is significant among multinational retail chains.
SWOT Analysis of the Digital Twin Retail Refrigeration Sector
Key strengths include real-time thermal visibility and massive energy savings. Weaknesses involve complex system integration hurdles. Opportunities lie in pharmaceutical cold-chain compliance, while threats stem from cybersecurity vulnerabilities in connected edge devices and cloud-based simulation platforms.
Value Chain Analysis from Raw Materials to End-Users
The value flow originates with semiconductor and raw metal suppliers for hardware components, progressing to device manufacturers like Carel Industries S.p.A. and BITZER Kühlmaschinenbau GmbH. Software developers then layer digital twin platforms before system integrators deploy solutions to end-user supermarkets.
Strategic Investment Insights and High-Potential Areas
Investors should target software providers specializing in AI and machine learning analytics for walk-in coolers. High-potential opportunities exist in retrofitting legacy convenience stores with low-cost edge monitoring devices to capture underserved mid-market segments.
Conclusion and Strategic Takeaways for Stakeholders
The Digital Twin Retail Refrigeration Market is transitioning from an experimental luxury to an operational necessity. Reaching $2.17 Billion by 2033, success favors agile software vendors and hardware manufacturers providing seamless interoperability and immediate regulatory compliance.
Proprietary Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level refrigeration executives, secondary macroeconomic indicators, trade registry data from major import-export hubs, and proprietary bottom-up modeling of retail chain technology budgets.
Scope of the Report and Analytical Parameters
This report covers global deployment metrics across hardware, software, and service segments within retail and pharmaceutical cold chains from 2026 to 2033. Limitations include localized variations in municipal electrical grid tariffs and proprietary data restrictions from privately held compressor manufacturers.
Recent Industry Developments, Partnerships, and Strategic Moves
Recent market activity highlights aggressive strategic partnerships between software innovators like Axiom Cloud Inc. and major refrigeration equipment builders. Companies are actively launching modular AI analytics suites designed to retrofit existing supermarket display cases without requiring total hardware replacement.